Munich, 21 September 2026 · Nexuswelt Group
Founders usually frame this as a choice, and investors sometimes encourage that framing. It is the wrong frame. Grants and venture capital are not substitutes – they buy different things, arrive on different timelines and carry different costs, and the strongest deep-tech companies in Europe use both.
What matters is sequencing, and one technical detail about ownership that can quietly remove your eligibility. Both are covered below.
They buy different things
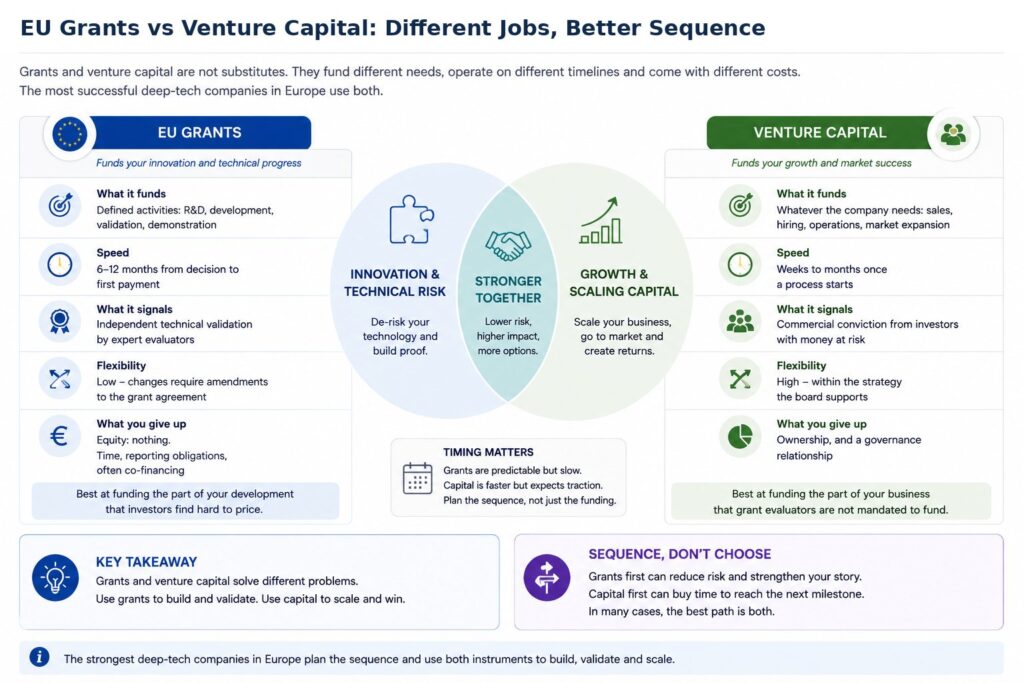
The clearest way to hold the distinction: a grant funds the part of your development that an investor would find hard to price. Venture capital funds the part that an evaluator has no mandate to fund.
What a grant actually costs
Non-dilutive does not mean free. The real costs are:
- Senior time. Six to twelve weeks of preparation for a serious application, and the parts that score cannot be delegated to an external writer.
- Co-financing, where the scheme requires it. Some instruments fund only a share of eligible costs, and that share has to come from somewhere identified before you apply.
- Reporting obligations that continue for the project’s life and, for dissemination and exploitation, beyond it.
- Reduced flexibility. The funded work is described in the grant agreement, and a strategic pivot mid-project is an amendment conversation rather than a board decision.
- Cash-flow exposure. Money arrives against progress, not in advance, and under lump sum funding payment is tied to completed work packages.
For a company whose main constraint is runway this quarter, that combination makes grants the wrong instrument regardless of how well the technology fits a call.
The timing problem
This is where the two most often collide. A grant timeline runs roughly twelve months from decision to first payment. A funding round can close in a fraction of that.
Two consequences follow. First, a grant cannot rescue a company that is short of runway – by the time it pays, the question has been settled some other way. Second, grant timelines can be planned around precisely because they are slow and predictable: you know when the cut-off is, roughly how long evaluation takes, and approximately when money would arrive. That predictability is worth more than it appears when it is used deliberately rather than hoped for.
The explicit combination: EIC blended finance
The European Commission has built the combination into one instrument. The EIC Accelerator offers a lump-sum grant below €2.5 million for innovation activities at TRL 6 to 8, together with equity investment through the EIC Fund, available as grant-only, blended finance or equity-only.
Some conditions are worth knowing before this becomes a plan:
- Grant-only support is awarded once per beneficiary across Horizon Europe, and capped at €2.5 million.
- You generally cannot apply while a previous EIC Accelerator or SME Instrument project is still running, with an exception allowing ongoing grant-only beneficiaries to apply for the investment component.
- Small mid-caps of up to 499 employees may apply, but only for the investment or blended route at high maturity – they are barred from grant-only support.
- The evaluation includes a jury interview, which is a different exercise from written assessment and where the gap between a proposal and a company becomes visible.
How a grant affects a raise
Founders overestimate the signalling value and underestimate the practical value.
What genuinely helps
- Non-dilutive money that carries the company to a higher-value milestone means raising later at a better valuation, or raising less.
- Independent expert evaluation is a real external validation of technical risk, which is the risk investors are least equipped to assess themselves.
- The discipline of writing an impact section – who uses this, through what route, and what has to be true – produces material that is directly reusable in investor conversations.
What does not help as much as founders expect
- A grant is not commercial validation. It says expert evaluators found the technology credible, not that anyone will buy it. Investors know the difference.
- A grant on the balance sheet does not offset a weak commercial story, and presenting it as though it does invites the wrong questions.
- Grant work can absorb the senior attention a raise requires. Running both processes in the same quarter is a recurring and avoidable mistake.
How a raise affects grant eligibility
This is the technical point most founders never hear, and it can remove eligibility without anyone noticing until verification.
Most startup-facing EU instruments require SME status under the EU definition: fewer than 250 employees, and either turnover not exceeding €50 million or a balance sheet total not exceeding €43 million. The complication is not the thresholds – it is that ownership structure changes how they are calculated.
| Category | What it means |
| Autonomous | No other enterprise holds 25% or more of capital or voting rights. Your own figures are used |
| Partner | Another enterprise holds between 25% and 50%. A proportional share of that enterprise’s headcount and financials is added to yours |
| Linked | Another enterprise holds more than 50%, or otherwise controls the company. Its figures are aggregated in full |
The aggregation is the trap. A company well inside the SME thresholds on its own can exceed them once a large investor’s figures are added, and thereby lose access to instruments that require SME status.
There is an important qualification, and it is the reason venture capital does not automatically destroy SME status: the EU definition treats certain investor types differently, and venture capital companies are among the categories that may hold between 25% and 50% without the company ceasing to be autonomous, provided they are not linked to it individually or jointly. Business angels, universities, non-profit research centres and certain institutional investors are treated similarly, within stated limits. Take-private control above 50%, or acquisition by a corporate, is a different matter.
Two practical consequences. SME status must be maintained throughout a funded project, not only at application – changes to ownership have to be reported, and an ownership change that undermines the basis of the award can be grounds for terminating the grant agreement. And because these rules turn on the precise structure of a cap table, this is a question to put to an advisor with the actual shareholder register in front of them rather than to resolve from a general article.
Sequencing that works
- Establish the TRL honestly. It determines which instruments exist for you and roughly where an investor will price the technical risk.
- Use non-dilutive money for the pre-commercial technical risk – validation, demonstration, certification. This is what investors find hardest to price and what grants exist to fund.
- Raise when the technical risk has fallen and the commercial story can be told. A grant-funded milestone is a better moment to raise than the same milestone funded by dilution.
- Do not run a grant application and a funding round in the same quarter. Both require the same senior attention, and each done badly costs more than either done well returns.
- Check the ownership implications before signing a term sheet, not after.
- Keep the cash-flow bridge in mind: grant money arrives against progress, so the working capital to reach each milestone has to exist independently.
Which fits your situation
| Your position | The realistic answer |
| Pre-commercial technology, technical risk dominant | Grants. This is precisely what they fund and what investors discount heavily |
| Working product, needs sales and hiring | Venture capital. No grant funds a sales team |
| Deep tech at TRL 6–8, ready to scale, high capital need | EIC blended finance – the combination is built into the instrument |
| Short of runway this quarter | Neither of these solves it. Bridge finance, revenue or national instruments with faster cycles |
| Strong technology, no European market presence | Grants plus a collaborative project – treat the project as market entry with funding attached |
| Already VC-backed with a large holder | Check SME status before assuming instrument access. The aggregation rules may have changed your position |
How Nexuswelt works with startups on this
The decision that matters is usually not which instrument but in what order, and it is best made before either process starts. Nexuswelt works with startups and SMEs on instrument selection, positioning and consortium entry, and contributes to funded projects as a partner for communication, dissemination and exploitation. The broader starting point is our guide to EU funding for startups, and more on the firm is on the Nexuswelt about page. Nexuswelt is not a financial or legal adviser; ownership and eligibility questions should be confirmed with a qualified professional.